Economic, Social, Cultural, and Environmental Rights as a Legal Framework for the Transition to Circular Production Systems in Emerging Countries: Foundations of Circular Economic Law
Keywords:
Environment, human rights, economic regulation, sustainable productionAbstract
This paper examines the role of Economic, Social, Cultural and Environmental Rights (ESCER) as a legal foundation for the transition toward circular production systems in emerging countries. It argues that the circular economy should not be understood merely as a technological or environmental transformation, but as an economic, social and legal restructuring guided by sustainability, distributive justice and human rights protection. From this perspective, the paper proposes the concept of Circular Economic Law as an emerging legal category aimed at articulating environmental law, international economic law and the right to sustainable development. The study identifies structural obstacles faced by developing countries, including poverty, labor informality, extractivism, inequality and technological gaps. It also examines the relationship between circularity and decent work, the right to a healthy environment, cultural rights, social equity and corporate responsibility. Finally, it proposes institutionalizing Circular Economic Law through constitutional and legislative reforms, economic incentives, education, multilevel governance and international cooperation
Author Biography
Jorge Witker, Universidad Nacional Autónoma de México
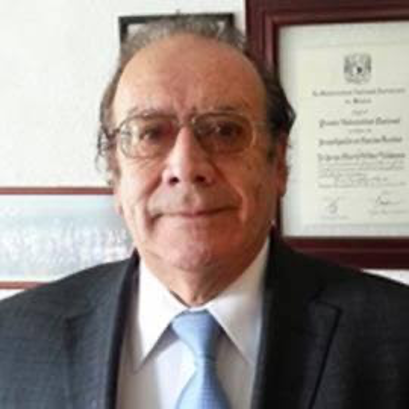 National Researcher Emeritus of Mexico and Academic of the Universidad Nacional Autónoma de México. Lawyer, Legal Degree from the University of Chile, Diploma in Comparative Law from the International Faculty for the Teaching of Comparative Law in Strasbourg, France, Doctorate in Law from the Complutense University of Madrid. Doctor Honoris Causa by the University of Valparaíso, Chile. ORCID ID: 0000-0003-0545-8988.Level III National Researcher since 1984. His primary areas of research are: Legal Research Methodology, Economic Law, International Trade, and Criminal Procedural Reforms in Latin America. In these fields, he has published over 80 books in Mexico and Ibero-America, as well as numerous articles and essays in both general-interest and scholarly journals, in Mexico and abroad. His recently published works include: Mining Law, Economic Criminal Law, and Economy and Economic Law.
References
Andres-Aucejo, E., Akamba, M. ., Nicoli, M. , & Owens, J. (Global Director) (2023, a). Toward a “Global Tax Legal Order” based on international tax cooperation, human rights and global tax governance for global sustainability, under United Nations centripetal force. UN Tax policy proposals (GLOVTAXORDER¬-UNTAXPOLICY). Review of International and European Economic Law, 2(3). Retrieved from https://www.rieel.com/index.php/rieel/article/view/36
Andrés-Aucejo, E. (2023b). Promotion of inclusive and effective international tax cooperation at the United Nations: About: The United Nations A/C.2/77/L.11/Rev.1 of the Second Commission of the General Assembly (23th November 2022); The United Nations A/RES/77/441 of the General Assembly (30th December 2022), and The report A/78/235 of the Secretary-General of the United Nations (26th July 2023).Review of International and European Economic Law,2(4), A5.1-A5.27. Retrieved from https://rieel.com/index.php/rieel/article/view/79
ANDRÉS-AUCEJO, Eva (main author), OWENS, J. (Director) 2023c. The universal institutionalization of International Tax Cooperation under United Nations orbit in the new architectural design of a Global Tax Legal Order inspired by International Tax Cooperation, human rights and global tax governance. Published by UNITED NATIONS.org Andrés-Aucejo, Eva and Owens, Jeffrey_Input Tax Report.pdf (un.org). https://financing.desa.un.org/sites/default/files/2023-03/Andr%C3%A9s-Aucejo%2C%20Eva%20and%20Owens%2C%20Jeffrey_Input%20Tax%20Report.pdf
Andres, E. (2024a). The new UN TAX CONVENTION ON INTERNATIONAL COOPERATION IN TAX MATTERS as an essential pillar of a new GLOBAL TAX ORDER designed through a NEW INTERNATIONAL TAX ORGANIZATION. Review of International and European Economic Law, 3(5). Retrieved from https://www.rieel.com/index.php/rieel/article/view/89
Andres-Aucejo, E. (2024b). Towards a Holistic UN Tax Convention (And Protocols), including Human, Economic, Social, Environmental and Cultural Rights: The “Substantive Issues” with Special Mention to Tax Education and Tax Compliance enhanced with Artificial Intelligence. Review of International and European Economic Law, 3(6), r1.1-r1.22. Retrieved from https://www.rieel.com/index.php/rieel/article/view/110
Andres, E. (2024c). The United Nations last trends on International Tax Cooperation: a new UN Tax Convention and a new International Tax Organization. Review of International and European Economic Law, 3(5). Retrieved from https://rieel.com/index.php/rieel/article/view/92
Andrés-Aucejo, E. and Masbernat, P. (2025a) The 4th International Conference on Financing for Development: international tax cooperation: Taxation and trade. Controls to fraud. IA in tax administration and Digital Services in the European Context. Agricultural GI Designations. Review of International and European Economic Law, 04 (nº 07) Retrieved from https://www.rieel.com/index.php/rieel/article/view/38/134
Andrés-Aucejo, E. (2025b) International tax cooperation and illicit capital mobilization as afirst (mathematical) derivative of the financing for sustainable development (FFD4): Proposals for the IV Conference on Sustainable Development Financing, with impact on taxation and trade/customs binomial. Review of International and European Economic Law, 04 (07) Retrieved from https://www.rieel.com/index.php/rieel/article/view/87
Backes, C. W. (2017). Law for a circular economy. Eleven Publishing, The Hage.
Boyle, A., & Anderson, M. (2020). Human Rights Approaches to Environmental Protection. Oxford University Press.
Circularity Gap Report (2022), Marc de Wit, Circle Economy, Netherlands.
Fernández Pons, X. (2022). Sustainable Development and Trade Treaties. Review of International and European Economic Law, 1(1), 68–83. Retrieved from https://www.rieel.com/index.php/rieel/article/view/12
García, L., & Pérez, M. (2021). Economía circular y justicia social en América Latina: desafíos y oportunidades. Universidad Nacional de Colombia.
Leff, E. (2018). Saber ambiental: sustentabilidad, racionalidad, complejidad y poder. Siglo XXI Editores.
Lesniewska, F. & Steenmans, K. (2023). Circular economy and the law: bringing justice into the frame. Taylor & Francis, New York.
Ministerio de Ambiente y Desarrollo Sostenible (Colombia). (2020). Política Nacional de Economía Circular. Bogotá: Gobierno de Colombia.
Organización Internacional del Trabajo (OIT). (2019). Empleos verdes y trabajo decente: panorama global. Ginebra: OIT.
Pardo, R., & Vanegas, F. (2020). Transición circular en economías emergentes: políticas, retos y lecciones aprendidas. CEPAL.
Programa de las Naciones Unidas para el Medio Ambiente (UNEP). (2022). Global Circularity Gap Report 2022. Nairobi: UNEP.
Ramos-Fuentes G. & Masbernat, P. (2021), Derecho al Desarrollo Sustentable en el marco de los ODS de la ONU. En Desarrollo Sustentable: Fundamentos Juridicos, P. Masbernat y H. Pacheco (eds.). Hammurabi, Santiago de Chile.
Saldívar Campos, A.I. (2018). "Producción y consumo responsable: Una necesidad inminente." Entretextos, 10(29): 1-23
Secretaría de Medio Ambiente y Recursos Naturales (SEMARNAT) (2021). Estrategia Nacional de Economía Circular de México (ENEC). Ciudad de México: Gobierno de México.
Sepúlveda, M. (2014). Derechos económicos, sociales y culturales: su exigibilidad y justiciabilidad en América Latina. Naciones Unidas.
Vega, C., & Muñoz, L. (2022). Economía circular y género: experiencias de mujeres recicladoras en Chile. Universidad de Concepción.
Downloads
Published
How to Cite
Issue
Section
License
Copyright (c) 2026 Jorge Witker

This work is licensed under a Creative Commons Attribution 4.0 International License.